IRS Notice CP504 in Waco: What Intent to Levy Means & Your 30-Day Rights
An authoritative, source-verified legal guide for Waco and Central Texas taxpayers holding an official IRS Notice of Intent to Levy.
Time to respond before administrative levy enforcement accelerates against wages and accounts.
Mandatory holding period under § 6332(c) during which frozen bank funds can be released before surrender.
No state refund offset exists in Texas; IRS enforcement targets private earnings directly.
1. Where Notice CP504 Sits in the IRS Collection Sequence
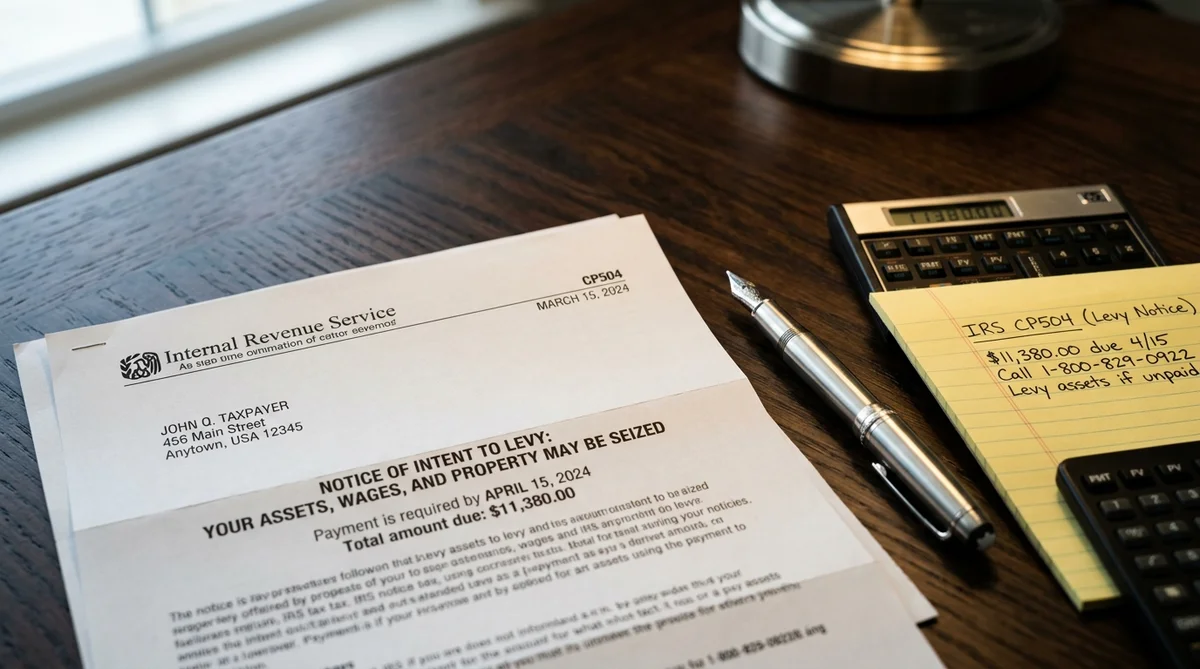
The IRS does not initiate seizures without formal statutory notice. Notice CP504 indicates that earlier demands for payment went unanswered, and automated billing is transitioning to administrative enforcement:
Initial balance-due demand. Taxpayer given 21 days (10 days if debt exceeds $100,000) to pay or enter an agreement.
Notice of Intent to Levy. Signals the final administrative warning before direct account seizure or wage withholding.
Final Notice with Collection Due Process (CDP) rights before levies are served on employers and banks.
2. Legal Distinctions: Levy vs. Lien vs. Wage Garnishment
Many taxpayers conflate tax enforcement terms. Understanding these legal differences is essential to protecting your assets:
| Enforcement Action | Statutory Authority | Mechanics & Asset Impact | Resolution Window |
|---|---|---|---|
| Notice of Intent to Levy (CP504) | 26 U.S.C. § 6331 | Warning notice before administrative seizure of cash and receivables. | 30 Calendar Days |
| Federal Tax Lien (NFTL) | 26 U.S.C. § 6321 | Public legal claim against real estate, vehicles, and business assets in McLennan County. | Precedes or accompanies levy |
| Bank Account Levy | 26 U.S.C. § 6332(c) | One-time freeze on bank funds at Waco financial institutions; 21-day holding period before surrender. | 21 Days from service |
| Wage Garnishment (Form 668-W) | 26 U.S.C. § 6331 | Continuous deduction from paycheck through employer payroll until paid or released. | Immediate every pay period |
Received a CP504 Notice in McLennan County?
Talk with a licensed Texas CPA or IRS Enrolled Agent today. Find out if your 30-day response window is still open and preserve your appeal rights.
Answered 24/7 · Connects with Circular 230 Licensed CPAs & IRS Enrolled Agents · No SSN Collected Online
3. Waco & Central Texas Specific Realities
No State Tax Refund Buffer: In other jurisdictions, taxpayers receiving CP504 frequently lose only an anticipated state income tax refund. Because the State of Texas does not impose a personal income tax, there is no state refund buffer. In Texas, the IRS moves directly toward commercial bank accounts (such as Extraco, TFNB, or Frost) and payroll withholding.
The Local Waco Taxpayer Assistance Center (TAC): While the IRS maintains a Taxpayer Assistance Center in Waco, in-person visits require appointment scheduling via 844-545-5640. Crucially, TAC personnel are clerical staff who process forms — they are legally prohibited from negotiating Offer in Compromise settlements, granting hardship relief, or acting as your advocate.
4. Four Immediate Steps to Protect Your Assets
Verify Postmark & Notice Date
Check the date printed on the upper right corner of your CP504. The statutory 30-day window begins on that notice date. Preserve the original postmarked envelope as legal proof of receipt.
Avoid Scams & Unsolicited Phone Calls
The IRS will never telephone demanding immediate payment with gift cards or commercial wires. Beware of aggressive sales companies promising to eliminate your debt for "pennies on the dollar."
Evaluate Legitimate Statutory Remedies
Depending on your financial condition under IRS Allowable Living Expense standards, options include Streamlined Installment Agreements, Currently Not Collectible (hardship) status, or an Offer in Compromise under 26 U.S.C. § 7122.
Engage a Circular 230 Licensed Representative
A licensed CPA or IRS Enrolled Agent can file IRS Form 2848 Power of Attorney to obtain an immediate collection hold while structuring an orderly defense.
Frequently Asked Questions: Notice CP504 in Texas
What is an IRS Notice CP504?
Notice CP504 is a formal Notice of Intent to Levy issued under 26 U.S.C. § 6331. It informs the taxpayer that the IRS intends to seize state tax refunds, bank accounts, wages, or other property to satisfy unpaid federal taxes unless resolved within 30 days.
How does Notice CP504 affect Texas taxpayers who don't have a state income tax refund?
In states with personal income taxes, the IRS first intercepts state refunds. Because Texas has no state personal income tax, an unresolved CP504 notice accelerates directly into federal administrative levies against employer payroll (Form 668-W) and bank checking/savings accounts.
Can an IRS CP504 levy be stopped in Waco?
Yes. By contacting the IRS Collections division or engaging a licensed CPA or IRS Enrolled Agent with Form 2848 Power of Attorney, taxpayers can request an administrative collection hold and establish an approved resolution such as an Installment Agreement, Currently Not Collectible status, or an Offer in Compromise.
Does visiting the local Waco IRS office stop a CP504 levy?
No. The Waco Taxpayer Assistance Center (TAC) operates by appointment only and its staff cannot negotiate settlement amounts, provide legal advocacy, or represent taxpayers against collection officers.
Don't Let Your CP504 Window Close Unanswered
Connect with a vetted, licensed Circular 230 practitioner serving Waco and McLennan County. Get clarity and stop enforcement before Day 30 expires.
Answered 24/7 · Connects with Circular 230 Licensed CPAs & IRS Enrolled Agents · No SSN Collected Online