IRS Tax Liens in Waco: Notice of Federal Tax Lien vs. McLennan County Property Taxes
When the IRS files a Notice of Federal Tax Lien with the McLennan County Clerk, it places a public cloud over your home, vehicles, and commercial assets. Understand how statutory liens work, why local McLennan County taxes hold "super-priority," and how licensed CPAs and Enrolled Agents can discharge, subordinate, or withdraw the filing.
Attaches automatically upon assessment & unpaid demand.
Statutory deadline to appeal filing via Form 12153.
McLennan County property taxes take seniority over federal liens.
Fresh Start direct-debit removal mechanism.
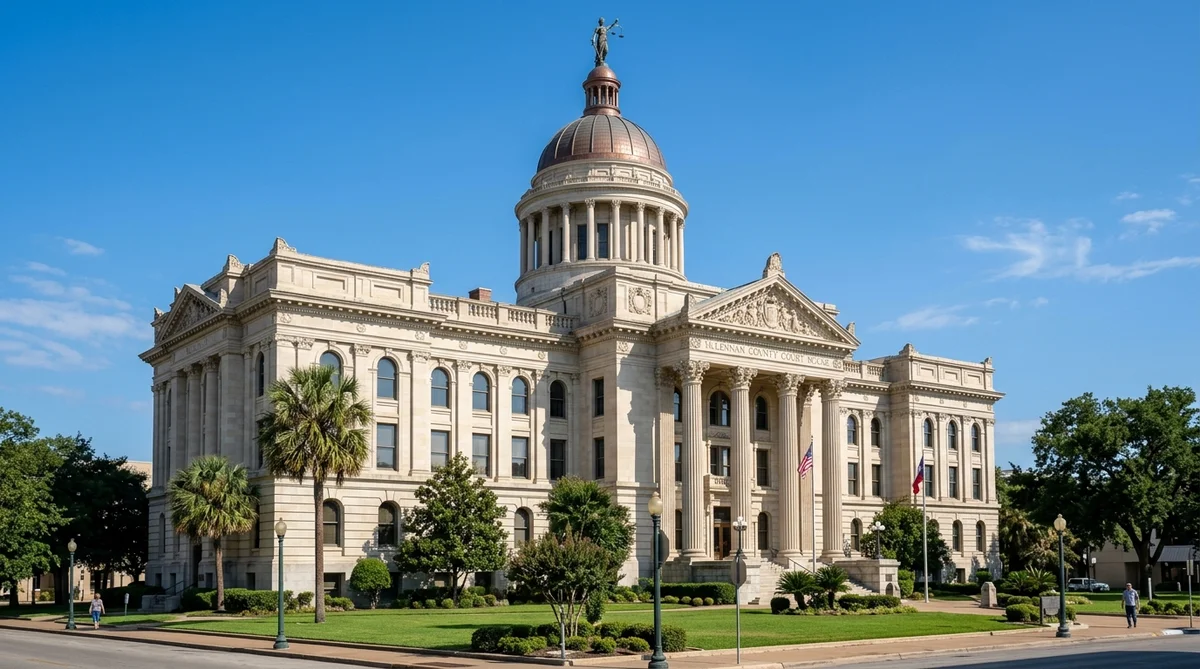
McLennan County Official Public Records
Historic Beaux-Arts Courthouse & County Records Building, 215 N 5th St, Waco, TX 76701
The "Secret" Statutory Lien vs. The Public Notice of Federal Tax Lien
Many Central Texas taxpayers are surprised to learn that an IRS lien actually exists long before any document is filed in the county records. Federal tax law establishes two distinct stages of lien attachment:
The Statutory Assessment Lien
26 U.S.C. § 6321
Sometimes called the "silent" or "secret" lien, this arises automatically by operation of law the moment the IRS formally assesses a tax balance, sends a demand for payment (such as a CP14 or CP504), and the taxpayer fails to pay in full. It attaches to all existing and future property rights without public notification.
Notice of Federal Tax Lien (NFTL)
26 U.S.C. § 6323
To establish priority over third-party creditors—such as mortgage lenders, vehicle lienholders, and mechanics' lien claimants—the IRS records an official NFTL with the county clerk. In McLennan County, this transforms the private tax debt into a matter of public record, alerting title examiners, credit underwriters, and commercial partners.
Comparison: IRS Federal Tax Lien vs. McLennan County Property Tax Lien
Property owners in Waco frequently confuse delinquent county ad valorem property taxes (owed to the McLennan County Tax Assessor-Collector) with federal tax liens (issued by the U.S. Department of the Treasury). The legal rules, priorities, and resolution mechanisms are completely distinct:
| Legal Characteristic | IRS Federal Tax Lien (IRC § 6321 / § 6323) | McLennan County Property Tax Lien (Tex. Tax Code § 32.01) | Actionable Resolution Strategy |
|---|---|---|---|
| Property Scope | Attaches to ALL real & personal property nationwide | Attaches strictly to the specific local real parcel | Comprehensive estate review |
| Statutory Priority | Subject to local property tax 'super-priority' (§ 6323b6) | Senior Super-Priority over federal liens | Verify lien seniority in title |
| Public Recording Venue | McLennan County Clerk (Official Public Records, Waco) | McLennan County Tax Assessor-Collector Records | Check recorded instrument numbers |
| Enforcement Nature | Security encumbrance; requires levy (§ 6331) to liquidate | In rem statutory tax lien; enforced via foreclosure | Intervene before collection turns to levy |
| Mitigation / Removal | Discharge (Form 14135), Subordination (Form 14134), Withdrawal (Form 12277) | County payment plan or redemption within statutory periods | CPA / EA representation |
The Super-Priority Doctrine: Why McLennan County Taxes Beat the IRS
Under standard common-law property rules, creditor priority is governed by the ancient rule of "first in time, first in right." However, Congress recognized that local governments depend on real estate taxes to fund schools, emergency services, and roads.
26 U.S.C. § 6323(b)(6): The Local Tax Super-Priority
Federal law explicitly subordinates an already-filed IRS Notice of Federal Tax Lien to local real property tax assessments. Under IRC § 6323(b)(6), if Texas state law grants local property taxes priority over previously recorded mortgages (which Texas Tax Code § 32.01 does), the local property tax lien takes statutory "super-priority" over the federal tax lien as well.
What this means for Waco property owners: If your home is facing foreclosure or liquidation, delinquent McLennan County property taxes will be satisfied from sale proceeds before the IRS receives a single dollar. However, having both liens creates complex title gridlock that requires careful coordination between county tax collectors and federal revenue officers.
Four Statutory Avenues to Release, Discharge, or Subordinate an IRS Lien
An IRS tax lien does not have to paralyze your financial life or prevent property transactions. Federal statutes provide four distinct legal mechanisms for relief:
1. Certificate of Lien Release (26 U.S.C. § 6325(a))
Complete ExtinguishmentThe IRS is legally mandated to issue a formal Certificate of Release (Form 668-Z) within 30 days of either: (a) the tax debt, penalties, and interest being paid in full; or (b) the 10-year statutory collection statute (CSED under 26 U.S.C. § 6502) expiring. Once recorded in McLennan County, the lien is fully dissolved.
2. Certificate of Discharge (26 U.S.C. § 6325(b) / Form 14135)
Permits Real Estate SaleIf you need to sell a home or commercial building in Waco, you can apply for a Certificate of Discharge. This releases the lien from that specific parcel of real estate while leaving the lien intact on your remaining assets. The IRS will approve the discharge if the net proceeds from the sale are applied toward the tax debt or if the government has zero equity interest in the property.
3. Certificate of Subordination (26 U.S.C. § 6325(d) / Form 14134)
Permits RefinancingMortgage lenders in Texas will not refinance a home loan if an IRS lien holds senior priority over their new deed of trust. By filing Form 14134, a licensed practitioner can request that the IRS agree to step into junior position behind the new lender, provided that the refinancing lowers payments or extracts cash to pay down the federal tax balance.
4. Complete Lien Withdrawal (Form 12277 / Fresh Start)
Removes Public RecordUnlike a release (which shows the lien was filed and later satisfied), a lien withdrawal expunges the public notice entirely, treating the NFTL as if it had never been filed. Under the IRS Fresh Start Initiative (IR-2011-20), taxpayers owing $25,000 or less who convert to a Direct Debit Installment Agreement (DDIA) can qualify for withdrawal after just three consecutive monthly debits.
The 30-Day Collection Due Process (CDP) Deadline
When the IRS files an NFTL, they are required under 26 U.S.C. § 6320 to send you official notice (Letter 3172) within 5 business days. This letter triggers an invaluable statutory right:
You have exactly 30 calendar days from the postmark date on Letter 3172 to file IRS Form 12153, requesting a Collection Due Process (CDP) Hearing before the IRS Independent Office of Appeals. A timely filed CDP request halts certain enforcement actions and gives a licensed CPA or Enrolled Agent direct legal authority to negotiate alternative collection resolutions—such as installment agreements, Currently Not Collectible status, or an Offer in Compromise.
Have Questions About an IRS Notice of Lien?
Talk directly with Maya, our automated voice assistant, or connect immediately with a Circular 230 licensed CPA or IRS Enrolled Agent serving McLennan County.
Frequently Asked Questions: Waco IRS Tax Liens
Does an IRS Notice of Federal Tax Lien mean the government is seizing my Waco home?
No. A tax lien is not a seizure (levy); it is a legal claim and public security encumbrance against your property equity. While a lien clouds your title and prevents you from selling or refinancing without resolving the debt, the IRS does not immediately auction your primary residence. Actual asset seizure requires a separate levy notice under 26 U.S.C. § 6331.
Where are IRS Federal Tax Liens recorded in McLennan County?
Federal tax liens are filed publicly with the McLennan County Clerk's Office (Official Public Records), located at the Records Building in downtown Waco. Once recorded, the lien attaches to all real property and titled assets owned within the county, as well as rights to property acquired in the future.
Which lien has priority: McLennan County property taxes or the IRS?
Under 26 U.S.C. § 6323(b)(6), local ad valorem real property taxes assessed by McLennan County and the City of Waco have statutory 'super-priority' over previously filed federal tax liens. This means county property tax liens are paid ahead of federal tax liens during real estate liquidations.
Can an IRS tax lien be withdrawn before paying the balance in full?
Yes. Under the IRS Fresh Start Initiative (IR-2011-20), qualifying taxpayers who owe $25,000 or less can convert their balance into a Direct Debit Installment Agreement (DDIA) and submit Form 12277. After three consecutive successful on-time bank debits, the IRS can withdraw the public Notice of Federal Tax Lien entirely, treating it as if it was never filed.
Can I sell or refinance my Waco home if I have an active IRS lien?
Yes, through two specific statutory mechanisms: (1) Form 14135 (Application for Certificate of Discharge of Property from Federal Tax Lien), which allows the specific home to be sold free of the lien if proceeds satisfy the IRS's equity interest; or (2) Form 14134 (Application for Certificate of Subordination), which permits a new mortgage lender to take priority over the IRS lien during a refinance.
Protect Your Waco Property & Clear Your Title
Do not let an IRS tax lien destroy your credit, freeze property sales, or escalate into an administrative bank levy. Speak with a vetted, Circular 230 licensed CPA or IRS Enrolled Agent today.
Answered 24/7 · Connects with Circular 230 Licensed CPAs & IRS Enrolled Agents · No SSN Collected Online